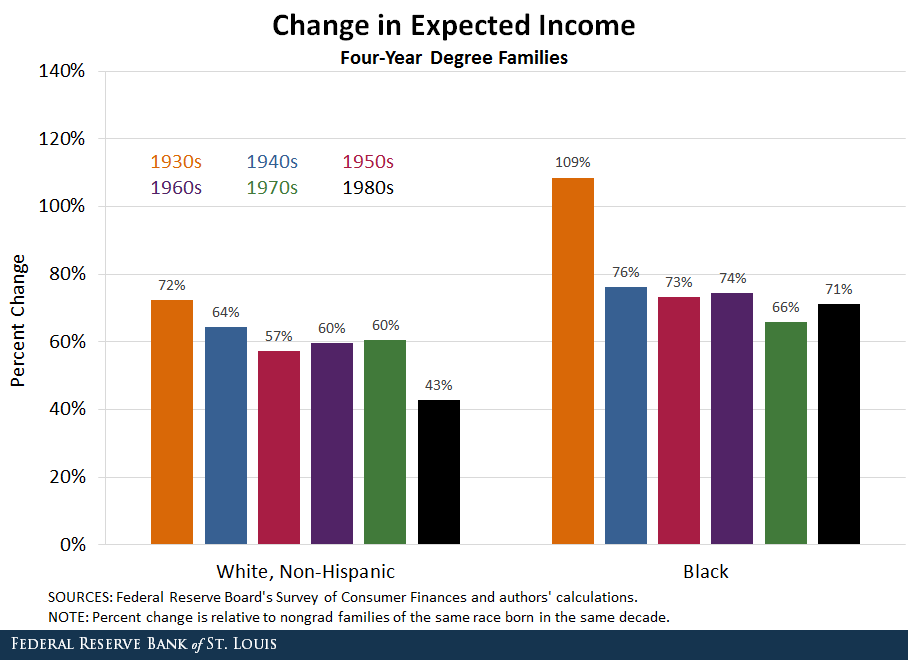
Showing posts with label END THE FED. Show all posts

Wednesday, July 18, 2018

The College Boost: Grads Still Outearn Nongrads | St. Louis Fed


College bonus 1
This is Part I of a three-part series from the Fed. A little more cheery than Part II, which I posted yesterday. I can't wait for Part III to see their solutions.
On average, families headed by someone with a four-year college degree have 69 percent more income and 201 percent more wealth than families without a degree. The gaps between nongrads and those with a postgraduate degree are even larger.
I fear they are going to bang the drums for equal funding for all school districts nationwide. It's all these socialists and Marxists know. They fail to realize and refuse to accept that even if you do that -- and there will be unintended/unforeseen consequences to doing that -- the race will still go to the swiftest and the fight to the strongest. That's the way to bet. 


from the St. Louis Fed:

The College Boost: Grads Still Outearn Nongrads


Monday, July 16, 2018


By William Emmons, Lead Economist; Ana Hernández Kent, Policy Analyst; and Lowell Ricketts, Lead Analyst, Center for Household Financial Stability
This is the first post in a series on the financial returns of college degrees.
A college degree has long been associated with a laundry list of positive outcomes:
  • Higher income and wealth
  • Better health
  • A higher likelihood of being a homeowner
  • A higher likelihood of being partnered (married or cohabitating)
  • A lower risk of falling behind on loan payments
In response, more and more Americans are pursuing—and earning—a bachelor’s degree. In 1989, about 23 percent of families were headed by someone with a four-year college degree or higher. By 2016, the share had reached 34 percent.
More individuals are continuing their schooling beyond the traditional four-year degree as well. Families headed by someone with a postgraduate degree (such as a master’s degree or Ph.D.) rose from almost 9 percent of all families in 1989 to about 13 percent in 2016.
This remarkable surge in highly educated individuals begs the question: How have the financial returns (expected earnings and wealth) of college degrees fared over time?

The Average Financial Returns to a College Degree


Previous work by our Center for Household Financial Stability has long corroborated the traditional wisdom that a college degree is associated with higher expected earnings and wealth.1 For this analysis, we typically used the Survey of Consumer Finances, often considered the gold standard of data on household balance sheets (asset, debt and income).
When evaluating the financial payoff to a college education, it is useful to ask: How much additional income and wealth does a college-educated family have beyond that of a family that doesn’t hold a college degree?

Income Differences


Pooling all available data (47,776 families), we found that the average family with a four-year degree (grads) earned approximately 69 percent more than the average family without a degree (nongrads). The average family with a postgraduate degree (postgrads) earned twice as much as their nongrad counterpart. Importantly, these estimates controlled for the age of the family, so we were comparing outcomes at similar stages of life.

Wealth Differences


What about wealth? College graduates—both grads and postgrads—accumulated much higher amounts of wealth over their lifetime than nongrads. On average, grad families accumulated 201 percent more, while postgrad families accumulated 242 percent more than their nongrad peers.
These boosts are remarkable, and it’s clear why going to college is such an imperative for individuals and families across the U.S. However, these average returns mask a considerably wide range of outcomes. How do these outcomes vary when considering the race and ethnicity as well as birth decade of these families? That will be the focus of the next post in this series.

Notes and References


1 For example, see Emmons, William R.; and Noeth, Bryan J. “Education and Wealth.” The Demographics of Wealth, Essay No. 2, May 2015.

Additional Resources


The College Boost: Is the Return on a Degree Fading? | St. Louis Fed

grad change expected income


I'm sure it's not the Feds fault, right?
On average, black college graduates born in the 1980s have little or no additional wealth above their counterparts without a degree. This is true for postgraduate degrees as well.
Get the Fed out of education and watch results go back to where they were before they put their hands on it.

But no!!  We'll continue to ask the arsonists to put out the fire. It appears we've definitely devalued or diminished, but not quite destroyed the value of an education in this country. God Bless America!!


from StLouisFed.org
https://www.stlouisfed.org/on-the-economy/2018/july/college-boost-return-degree-fading

The College Boost: Is the Return on a Degree Fading?


Tuesday, July 17, 2018

This is the second post in a series on the financial returns of college degrees.
By William Emmons, Lead Economist; Ana Hernández Kent, Policy Analyst; and Lowell Ricketts, Lead Analyst, Center for Household Financial Stability
Our May research symposium, “Is College Still Worth It: Looking Back and Looking Ahead,” identified how the returns to a college degree have changed over time and how those returns can be boosted going forward.
For our Center’s research contribution, we focused on how the financial returns to college have changed across generations. We concentrated on income and wealth outcomes for college graduates born in six decades:1
  • 1930s
  • 1940s
  • 1950s
  • 1960s
  • 1970s
  • 1980s
Among racial and ethnic groups, we had a large enough sample to break out our results for non-Hispanic white families and African-American or black families. Similar to the first post in this series, we looked at the boost to income and wealth associated with both four-year (grads) and postgraduate (postgrads) college degrees.

Expected Boost to Income Remains Strong

The figure below shows that expected incomes among grad families of either race have largely held steady across birth cohorts, with the exception of white grads born in the 1980s.
change expected income
Certainly, the returns were highest among older generations. By our measure, the 1930s generation benefited marvelously from earning a four-year degree. Incomes of grads born in the ‘30s were 72 percent and 109 percent higher than their nongrad peers for white and black families, respectively.
However, given statistical uncertainty or “noise,” we can’t definitively say that the incomes of grads born in the ‘30s were meaningfully higher than grads born in the ‘40s through ‘70s. This tells us that the expected boost to earnings associated with a four-year degree remains largely unchanged over time.
We can say that for white grads born in the ‘80s, their incomes were meaningfully lower than those of previous generations. However, it’s important to note that even the ‘80s grads received a sizable boost to their income. Thus, it appears that grad families of either race, born in any decade, reaped sizable rewards in the labor market.
What about postgraduate degrees? The next figure offers a similar look at the income boost among these highly educated families.
grad change expected income
Expected earnings associated with a postgraduate degree have declined somewhat over time among white families. Returns peaked at 108 percent higher income for postgrad families born in the '30s and gradually shifted down to 54 percent for the postgrads born in the '80s.
Among black postgrads, the earnings boost is considerably more volatile across generations. After looking at the statistical noise related to these estimates, we can’t say that the boost to black postgrad income has meaningfully changed over time.
Again, the '80s are a peculiar decade: Similar to their four-year degree counterparts, white postgrads born in the '80s have a lowest income boost than those born in the previous five decades.

The Wealth Advantage Is Falling

The majority of conversations involving the return to a college degree talk about what graduates earn in the job market following school. This is certainly important, and the evidence suggests that graduates continue to have superior incomes over their lifetime.
What is often obscured is how those graduates accumulate wealth over their lifetime. This is an important difference: Research has shown that assets—financial (such as stocks) and nonfinancial (such as a home)—are profoundly important for both financial security and upward mobility.
If wealth is so important, why is it left out of the conversation? Reliable and nationally representative household balance sheet data are notoriously hard to come by. It is precisely this reason that the Federal Reserve Board’s Survey of Consumer Finances (SCF) is such a valuable resource. Using SCF data, we found that the boost to wealth accumulation associated with college has fallen across generations.
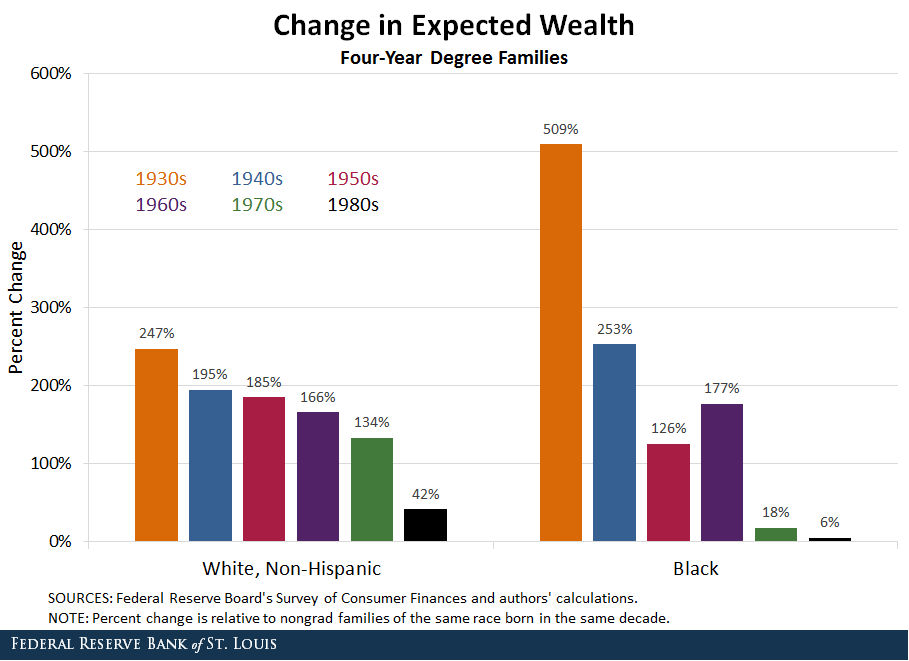
The wealth advantages afforded grad families, white and black, are shown in the figure below.
change expected wealth
A similar trend emerges: Grad families born in previous generations received a much greater boost to wealth accumulation than their nongrad peers. White and black grads born in the ‘30s accumulated 247 percent and 509 percent more wealth, respectively. This compares with 42 percent and 6 percent more wealth for white and black grads born in the ‘80s.
Black graduates born in the ‘70s also accumulated on average a historically low amount of wealth (18 percent) above their nongrad peers. Disturbingly, given the statistical uncertainty around our estimate for the wealth boost among black grads born in the ‘70s and ‘80s, we can’t say for certain that there even is a wealth advantage to a college degree for the average black family.
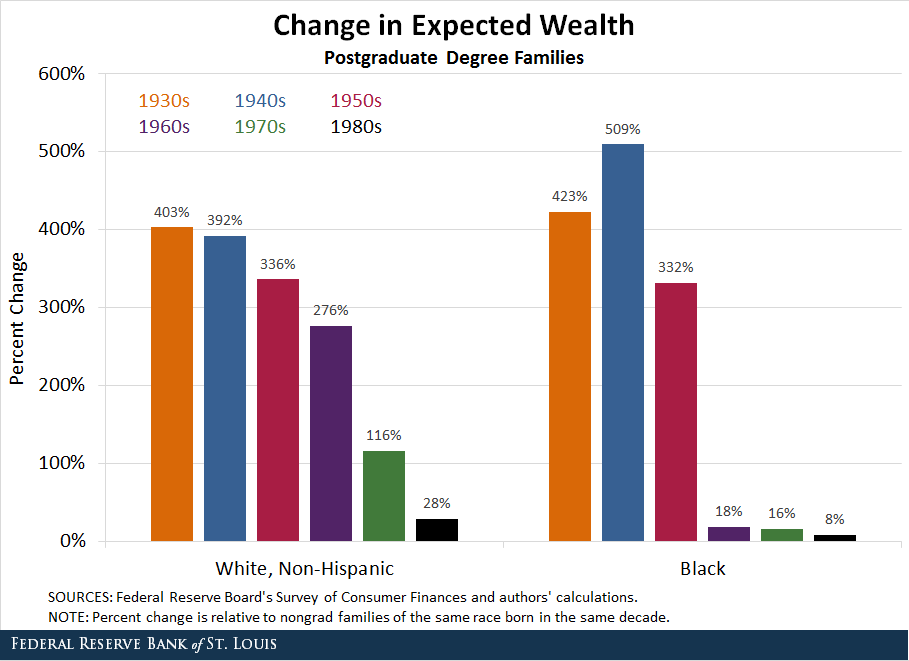
The fortunes of families holding postgraduate degrees are even dimmer by our estimates, as seen in our next figure.
grad change expected wealth
The enormous expected boost to wealth deteriorates rapidly between the ‘50s and ‘80s generations. Among white postgrads, the wealth boost ranged between 403 percent and 276 percent for postgrads born in the ‘30s through ‘60s.
Compare that with those born in the ‘70s and ‘80s, which had 116 percent and 28 percent higher expected wealth than nongrads. The boost estimated for white grads born in the ‘80s is almost negligible after accounting for statistical noise.
The picture is similar for black postgrads, although the decline in the wealth boost starts among postgrads born in the ‘60s. Black postgrads born in the ‘50s accumulated 332 percent more than their nongrad peers. Postgrads born in the ‘60s, ‘70s, and ‘80s accumulated only 18 percent, 16 percent and 8 percent, respectively, more than their nongrad peers.
All of those estimates were sufficiently noisy that we can’t rule out that they could be zero or even negative. The implication is shocking: Black postgrads born in the 1960s, ‘70 or ‘80s do not have statistically higher wealth than blacks who didn’t graduate from college.
Why have the wealth returns to both a four-year and postgraduate degree fallen so precipitously across birth cohorts while earnings have fared far better? The third and final post in this series will offer some potential explanations.

Notes and References

1 Our sample was too thin among families born before the 1930s and after the 1980s to provide reliable estimates.


Friday, September 04, 2015

Fed official: No evidence QE boosted economy


Once again, your tax dollars at work, After all these years of the tin-foil hat wearing crowd saying this QE stuff was crazy and being excoriated as for it, now they finally admit that it didn't work? Maybe we should turn to the people who have been more consistently right, rather than the dolts who have been consistently wrong about so many things.

Subject: CNBC - Fed official: No evidence QE boosted economy
Fed official: No evidence QE boosted economy
The Federal Reserve is putting some of its post-crisis actions under a magnifying glass and not liking everything it sees.
Read more: http://www.cnbc.com/id/102929090
Sent from the CNBC app. Available on the App Store

Sent from my iPhone

Monday, June 29, 2015

FINANCIAL RULES OF THUMB

image
Here's why renters in America feel trapped
In a recent report by the FINRA Investor Education Foundation, researchers offer a sobering peek into the homes (and finance) of renters. It's not a prett...
Preview by Yahoo


Presented as a public service.

Some financial Rules of Thumb that regular folks should know in order to negotiate their way through the Great Financial Crisis (GFC) or as it's more commonly referred to by those that want more control over you life, the greatest financial crisis since the Great Depression.

BTW: those folks fail to inform you that both events were brought to you by the same folks that we are told we have to turn to in order to get us out of the crisis ( The Federal Government and The Federal Reserve ). A paradox indeed.

If we had not jettisoned some of these "rules of thumb" as relics of a bygone era in the name of expediency (mostly politicial, combined with personal), heck we may not have had a Great Financial Crisis to begin with. WDIK? ¯\_( )_/¯

As we have illustrated before: Education, Employment, Marriage lead to higher standard of living.

THE THREE "GET AND STAYS":
Get educated and stay educated.
Get employed and stay employed.
Get married and stay married

Very easy to see here in this report. 

Source: Finra


Things aren't looking great for aspiring homeowners in the U.S.
In a recent report by the FINRA Investor Education Foundation, researchers offer a sobering peek into the homes of renters. Nearly one-quarter of renters  in a survey of 25,509 renters and homeowners combined say meeting their monthly financial commitments is "very difficult," and more than half say they wouldn't be able to come up with $2,000 to cover an emergency expense.
Homeowners, by comparison, feel much more stable. Half as many homeowners as renters say they find meeting their monthly bills "very difficult" and nearly half say they have no trouble meeting their monthly expenses, according to the report.
Because the cost of renting and buying varies so widely across the U.S., you have to take reports like these with a healthy dose of salt. In some metro areas, like San Antonio and Phoenix, it's actually much cheaper to buy a home than rent.  
But the reality is that the cost of renting across the country is on the rise, straining the budgets of many renters. In the largest 25 metro areas in the U.S., rents increased by 5.5% in 2013, eating up more than 40% of the average renter's household income, according to Trulia. Most financial experts recommend spending less than one-third of income on housing.
"Once [rent] is over 30%, that's when you start getting into the danger zone financially," says Helen Stephens, a certified financial planner in Dallas. "And the problem when you're renting is that you may be in a lease for a year, and at the end of that year your landlord has the right to raise the rent on you."
In addition to rising rents, coming up with the cash for day-to-day expenses, let alone a down payment, can be tough for renters. Renters are more likely to be saddled with debt of all kinds than homeowners, according to FINRA. More the half of renters carry credit card debt vs. 47% of homeowners. And renters are nearly twice as likely to have medical debt than homeowners, owing to the fact that fewer renters have health insurance.
Not all renters are 20-somethings eating Cup Noodles and struggling to pay off student debt, either. The average age of renters today is 41, per FINRA, and nearly half of renters say they have dependents at home.
The road from rent to mortgage 
For renters who aspire to own a home one day, the biggest hurdle they'll face is mastering cash flow — ensuring that the money coming in can not only cover their bills, but also leave them with wiggle room to save. Unfortunately, today's renters have a lot less capital to work with than existing homeowners. According to FINRA, 74% of renters earn less than $50,000 a year, vs. 60% of homeowners who earn more than $50,000.
Another challenge facing prospective homebuyers: the daunting down payment -- typically 20% of the home's purchase price. And Stephens advises her clients to build up an emergency maintenance fund of at least a few thousand dollars in case any unexpected repairs are needed once they've moved in.
As for the best place to save for a down payment, Stephens recommends a regular bank account. Banks are offering paltry interest rates on savings now, but it's a wiser option than investing it in the stock market, she says.
"I don't believe in investing money in the market that you're going to need for the short term," she says. "I know it may not earn much [interest] in a bank but it is secure and it's for a very targeted expense."
Preparing financially isn't the only step to homeownership. Buying a house is a complex, long-term endeavor that requires a lot of mental prep work. In a FINRA survey of more than 25,000 homeowners and renters, 40% of renters answered a basic question about 15-year and 30-year mortgages incorrectly, compared to just 19% of homeowners. 
"No one should buy a home if they can't understand basic finance," says Ilyce Glink, author of "100 Questions Every First-time Home Buyer Should Ask". "The quick way to bankruptcy is to buy a house you can't afford, get locked into mortgage payments, real estate tax bills, and maintenance and upkeep expenses."
Glink has written dozens of articles available for free with tips for first-time homebuyers. But even she recognizes that homeownership isn't for everyone. Sometimes, renting just makes more sense.
"Choose renting if you don't know where you're going to want to live in five years, if your employment situation isn't stable, and if you can't currently set aside 20% of your after-tax income into a savings account," she says. "You might also choose renting if you're currently dating someone and hope to be in a long-term stable relationship that involves living together because otherwise you might buy a condo that's too small for your expanding family."


Source: FINRA


===

image
30 Personal Finance Rules of Thumb
Personal finance rules of thumb. Rules of thumb. Money rules of thumb, investing rules of thumb, car buying rules of thumb, debt rules of thumb, car main...
Preview by Yahoo

So here are the "Personal Finance Rules of Thumb" that I could find, with my comments in brackets:
  1. You should spend no more than 2-3 times your household salary on a house. [I think your mortgage should be no more than 3 times your household salary as a maximum. Any equity/down payment you have should be taken into account in this Rule of Thumb]
  2. In order to retire comfortably at a normal age, your net worth should be your age times your salary, divided by ten. [I don't remember the footnotes that go with this Rule, but it is from The Millionaire Next Door. If your net worth is twice that number or more, then you are a Prodigious Accumulator of Wealth and you'll be very comfortable in an early retirement. Discuss.]
  3. Every dollar in your RRSP in your twenties corresponds to a dollar of yearly income after 65 (adjusted for inflation). Every $2 in your RRSP in your thirties corresponds to a dollar of yearly income after 65 (adjusted for inflation). Every $4 in your RRSP in your forties corresponds to a dollar of yearly income after 65 (adjusted for inflation). Every $8 in your RRSP in your fifties corresponds to a dollar of yearly income after 65 (adjusted for inflation). […Until at 65-ish, you should have around $25 in your RRSP for every dollar of income (equates to 4% withdrawal rate). I can't remember what the assumptions were. But not hard to figure out I guess…Using the rule of 72, it implies a real return of 7.2% in your RRSP. Perhaps a bit high, but not completely unreasonable.]
  4. Maximum mortgage payments should be no more than 28% of your gross monthly salary. [I think this is what the banks use.]
  5. Maximum for all debt payments should be no more than 36% of your gross monthly salary. [Again, I think this is from banks]
  6. If you negotiate a discount of prime, a variable rate mortgage will always be cheaper in the long run when compared to a fixed-rate mortgage. [I think this is true.]
  7. Pick a variable rate mortgage, but increase your payments so that they match the fixed rate payments. [This one is from Gordon Pape I think. Gives you a safety cushion if rates go up, and you're prepaying the mortgage if rates stay the same or go down.]
  8. In addition to maxing out your retirement plans, try to save at least 10 percent of your take-home pay for other goals, such as an emergency fund, college or a new home. [Makes sense, a lot of PF books have said the same thing]
  9. Generally speaking, if you've got young kids or teenagers, you'll need a life insurance policy that covers between 6 and 10 times family income and possibly more, depending on your family's expenses and how much your surviving spouse can earn. [I'm sure everyone will point out that it is not income that matters, but expenses.]
  10. To find the percentage of your portfolio that should be invested in stocks, Subtract your age from 120. This formula should help you maintain your living standard through your retirement years. [The rule used to be 100 minus your age, but people are living longer I guess!]
  11. Student loans: "Your total borrowing shouldn't exceed what you expect to make your first year out of school." [I don't know what the basis is for this rule. Should be doable in Canada, unless you take 12 years of university]
  12. Buy used and drive it for at least 10 years. [Sure, this will probably save a lot of money]
  13. If you must borrow to buy a car, follow the 20/4/10 rule." Which means: Make a 20% down payment, don't borrow for more than four years and don't agree to a monthly payment that's more than 10% of your income — or 8% if you plan to buy a home in the next few years. [I reckon no one here has heard of the 20/4/10 rule, but there you have it, plain as day. The 20/4/8 rule must be to keep your debt payments reasonable when including the mortgage payment]
  14. To compute and compare the real monthly cost to buy, insure and operate a car, double the price tag and divide by 60. [I think this rule is way off. Maybe it's more like 120. Of course, this doesn't take in to account the amount of mileage you put on the car every month]
  15. Insure yourself for catastrophic expenses, not the stuff you can cover out of pocket. [Absolutely. Why get extended insurance on a $110 bread maker? Insurance is to protect wealth, not create it]
  16. If you can't afford to buy the house using a 30-year fixed-rate mortgage, you can't afford the house. [Clearly an American Rule of Thumb. Wonder if it still applies using the standard Canadian 25-yr fixed. And is this based on the posted rate or the negotiated rate?]
  17. It will save you money if you buy the right size refrigerator-freezer for your family. You need a total of 8 cubic feet of space for two people, plus 1 foot for each additional family member. [That doesn't seem like a whole lot of space. I know family fridges are around 22 cu ft. So unless these families are meant to have 16 family members, something's amiss here. Mind you, I have a 22 cu.ft fridge and there's only a sprinkling of condiments inside. I'm sure a membership to Costco will remedy the situation.]
  18. As a rule, your collision deductible should equal one week's take-home pay. [If that's true, then I suspect most people have way too high of a collision deductible. Does anyone know how much you'd save by moving from $500 to $1000 deductible? I vaguely remember a rule of thumb about collision coverage where if you pay more in a year on collision coverage than your car is worth, pass on it. Or maybe it was 2 years. Either way, if the car is 2000 model year or newer it's going to cost $2500 minimum to fix anything.]
  19. When traveling, take twice the money and half the clothes you think you will need. [Yup]
  20. Each degree you lower your thermostat over the winter will lower your overall heating bill by three percent. [Certainly a rule of thumb as the amount of savings will vary as to the temperature difference between inside and out. Wonder if its Fahrenheit or Celsius??]
  21. The end of April is the best time to get your car serviced because it's the slowest time for auto mechanics. The mild weather makes people feel more confident about their cars, and many can't afford car repairs because they've just paid income taxes. [Hmmm, maybe…Anyone confirm this?]
  22. Always wash your car before taking it in for service. Mechanics are more likely to take advantage of you if your car looks like it needs "everything." [Find a good mechanic first and you can skip the car wash]
  23. Cars with four doors are cheaper to repair than cars with two doors, but two-door cars are stolen twice as often as four-door models. [This is probably due to a broad generalization since 2 door cars are more likely to be expensive sports cars]
  24. The highest price you should pay for a car you're buying with a car loan is one-half your annual gross income. [See the 20/4/10 rule in #6.]
  25. It pays to turn off your engine if it will be idling for more than one minute. [Definitely. And good for the environment too. I think with newer cars you can cut that time down to 10 seconds. I know in Germany, they are required by law to turn their cars off at red lights.]
  26. The best time to buy a new car is the last day of the month because the sales staff wants their monthly reports to look good and is more likely to bargain. You can increase your chances of getting a good deal by choosing the youngest salesperson on the floor. [Sounds logical. But when you combine this with the other car-themed Rules of thumb, buying a car seems VERY complicated.]
  27. The time it takes to clean off the windshield is the time it takes to warm up your engine. [Agreed. Even from -40C with no block heater, all the engine needs is 30 secs maximum. On a regular winter day, I give it about 10secs, assuming there's no snow to remove. The cab will heat up much faster if the engine is actually working, and it doesn't work too hard when sitting and idling.]
  28. When traveling under 50 mph, it is more efficient to drive with the windows open than with A/C on. Above 50mph, it is more efficient (and comfortable and quiet) to drive with the A/C on. The drag is much worse with the windows open at higher speeds. [I think this is true. Didn't Mythbusters do a show on this?]
  29. Ethanol stores about 2/3 the energy of gasoline. Therefore, a 15% ethanol blend will reduce your mileage by 5%. [I think it decreases the harmful NOx emissions, so maybe it's a wash? Probably not.]
  30. There is a good rule for what temperature to buy gasoline at (the pumps are calibrated at a given temperature, 15C usually). Buy it above that temperature and you'll get more for free, buy it below that temperature and you'll get less than the pump says (why you can sometimes fill a 60L tank with 62L). [I just made this one up. But I do recall this discussion from a course on Engineering Measurements. Something to do with the density change affecting the flow meter.]

--

image
MintLife Blog | Personal Finance News & Advice | The To...
Mintlife Learn about Mint.com or Sign Up | Log in Categories Consumer IQ Goals Investing Style Credit Housing Planning Trends Family
Preview by Yahoo
Save at least 10% of your income.

Save at least three months of living expensed in an emergency fund.
Get a life insurance policy worth at least 6 times your household income.
Use the 20/4/10 rule when buying a vehicle.
Save 20 times your gross income for a comfortable retirement.
The 4% rule says you start taking 4% out of your savings the year after you stop working. You then withdraw the same amount adjusted for inflation, which typically runs 3%, each year after that.
Put down 20% on a house and don't borrow more than two times your income.
Another general rule says your mortgage should be no more than two times your household income.
Subtract your age from 100 to determine what percentage of your portfolio should be in stocks.
Pay off highest interest rate debt first.
Max the match on your 401(k).
Don't take out more in student loans than you expect to make your first year on the job.
Taking out $120,000 in student loans to earn $35,000 per year could create a financial ball and chain that could weigh you down for more than a decade.
"Before you get your doctorate in philosophy, think about what you're going to do with it," says Adam. "It's a lot more fun to be able to pay your rent and your car note than to be living in mom's basement when you're 40."
Craig Guillot is a business and personal finance writer from New Orleans. He covers insurance, investing, real estate, retirement and debt. His work has appeared in such publications and web sites as Entrepreneur, CNNMoney.com, CNBC.com, Bankrate.com and Investor's Business Daily. He is the author of "Stuff About Money: No BS Financial Advice for Regular People."

---


The standard rule of thumb is to save at least 10% of your income. 
As a rule of thumb, I figure that inflation runs 3.5% per year.
Invest no more than 10% of your total savings in your employer's stock. 
Perhaps the granddaddy of all financial rules of thumb is the rule of 72.
To determine how long it will take an investment to double, divide 72 by the annual return. 
As a rule of thumb,tackle big expenses before small expenses.

When getting a new mortgage, the balance should be less than 2x your family annual income.
Your housing costs should be less than 28% of your gross income, and your total monthly debt payments should be less than 36%. 

Standard advice was to consider refinancing your home if interest rates dropped by 2%. Closing costs are lower today, and now it often makes sense to refinance your home when interest rates have dropped by 1% from your current mortgage. 

One common rule of thumb when purchasing a car is to buy used, or to buy new and to drive it for ten years. Either one will save you big money. 

The 20/4/10 rule of thumb for buying a car. You should pay at least 20% down, finance for no more that four years, and the payment should be less than 10% of your income. The first part of this rule prevents you from owing more than the car is worth, and the last two parts prevent you from buying more car than you can afford. 
To approximate a new vehicle's five-year cost of ownership (in monthly terms), double the price tag and divide by 60.

It almost always makes more financial sense to repair your car than to buy a new one.
Save for your own retirement before saving for your children's college education. 
They can get loans for school. You can't get loans for retirement. When you're saving, remember the following:
The standard advice is to aim to replace 80% of your pre-retirement income. I think this rule is lame because it focuses on income and not expenses. Income is irrelevant. It's what you spend that matters. Instead, I recommend a different rule of thumb:
Base your retirement needs on 100% of your pre-retirement expenses — plus 10%.
Save about 20x your gross annual income to retire.

If you expect to withdraw from your portfolio for 40 years or more, you can probably safely withdraw and spend 4% of its value every year. 

IF you get a windfall, use 1% to treat yourself. (Or maybe 2% tops.) Put the rest in a safe place and ignore it for six months. After you've had time to think about it, make your decisions. 

Strictly speaking, rules of thumb deal with numbers. Still, there are a lot of non-numeric guidelines that I think are useful to know. Here are a few:
  • Always take the employer match on the 401(k).
  • Never touch your retirement savings — except for retirement.
  • Never co-sign on a loan.
  • Avoid paying interest on anything that loses value. (Note that under normal conditions, home values appreciate slowly, so they're not included in this guideline.)
  • Don't mess with the IRS. When it comes to taxes, don't try to cheat. Pay what you owe. Claim all the deductions you deserve, but don't try to stretch things.
  • In general, save an emergency fund first; pay off high-interest debt second; and begin investing (at the same time you pay down remaining debt) last.
  • If you're not willing to pay cash for it, then it doesn't make sense to buy it on credit.


Giants Top Minor League Prospects

  • 1. Joey Bart 6-2, 215 C Power arm and a power bat, playing a premium defensive position. Good catch and throw skills.
  • 2. Heliot Ramos 6-2, 185 OF Potential high-ceiling player the Giants have been looking for. Great bat speed, early returns were impressive.
  • 3. Chris Shaw 6-3. 230 1B Lefty power bat, limited defensively to 1B, Matt Adams comp?
  • 4. Tyler Beede 6-4, 215 RHP from Vanderbilt projects as top of the rotation starter when he works out his command/control issues. When he misses, he misses by a bunch.
  • 5. Stephen Duggar 6-1, 170 CF Another toolsy, under-achieving OF in the Gary Brown mold, hoping for better results.
  • 6. Sandro Fabian 6-0, 180 OF Dominican signee from 2014, shows some pop in his bat. Below average arm and lack of speed should push him towards LF.
  • 7. Aramis Garcia 6-2, 220 C from Florida INTL projects as a good bat behind the dish with enough defensive skill to play there long-term
  • 8. Heath Quinn 6-2, 190 OF Strong hitter, makes contact with improving approach at the plate. Returns from hamate bone injury.
  • 9. Garrett Williams 6-1, 205 LHP Former Oklahoma standout, Giants prototype, low-ceiling, high-floor prospect.
  • 10. Shaun Anderson 6-4, 225 RHP Large frame, 3.36 K/BB rate. Can start or relieve
  • 11. Jacob Gonzalez 6-3, 190 3B Good pedigree, impressive bat for HS prospect.
  • 12. Seth Corry 6-2 195 LHP Highly regard HS pick. Was mentioned as possible chip in high profile trades.
  • 13. C.J. Hinojosa 5-10, 175 SS Scrappy IF prospect in the mold of Kelby Tomlinson, just gets it done.
  • 14. Garett Cave 6-4, 200 RHP He misses a lot of bats and at times, the plate. 13 K/9 an 5 B/9. Wild thing.

2019 MLB Draft - Top HS Draft Prospects

  • 1. Bobby Witt, Jr. 6-1,185 SS Colleyville Heritage HS (TX) Oklahoma commit. Outstanding defensive SS who can hit. 6.4 speed in 60 yd. Touched 97 on mound. Son of former major leaguer. Five tool potential.
  • 2. Riley Greene 6-2, 190 OF Haggerty HS (FL) Florida commit.Best HS hitting prospect. LH bat with good eye, plate discipline and developing power.
  • 3. C.J. Abrams 6-2, 180 SS Blessed Trinity HS (GA) High-ceiling athlete. 70 speed with plus arm. Hitting needs to develop as he matures. Alabama commit.
  • 4. Reece Hinds 6-4, 210 SS Niceville HS (FL) Power bat, committed to LSU. Plus arm, solid enough bat to move to 3B down the road. 98MPH arm.
  • 5. Daniel Espino 6-3, 200 RHP Georgia Premier Academy (GA) LSU commit. Touches 98 on FB with wipe out SL.

2019 MLB Draft - Top College Draft Prospects

  • 1. Adley Rutschman C Oregon State Plus defender with great arm. Excellent receiver plus a switch hitter with some pop in the bat.
  • 2. Shea Langliers C Baylor Excelent throw and catch skills with good pop time. Quick bat, uses all fields approach with some pop.
  • 3. Zack Thompson 6-2 LHP Kentucky Missed time with an elbow issue. FB up to 95 with plenty of secondary stuff.
  • 4. Matt Wallner 6-5 OF Southern Miss Run producing bat plus mid to upper 90's FB closer. Power bat from the left side, athletic for size.
  • 5. Nick Lodolo LHP TCU Tall LHP, 95MPH FB and solid breaking stuff.